Moneylender Is Back, Rural India Stares At Deep Crisis
NABARD survey shows only 27% of rural households saw income rise in July 2026, while informal borrowing and moneylenders make strong comeback, writes CR Sukumar.
Published : September 2, 2026 at 5:30 PM IST
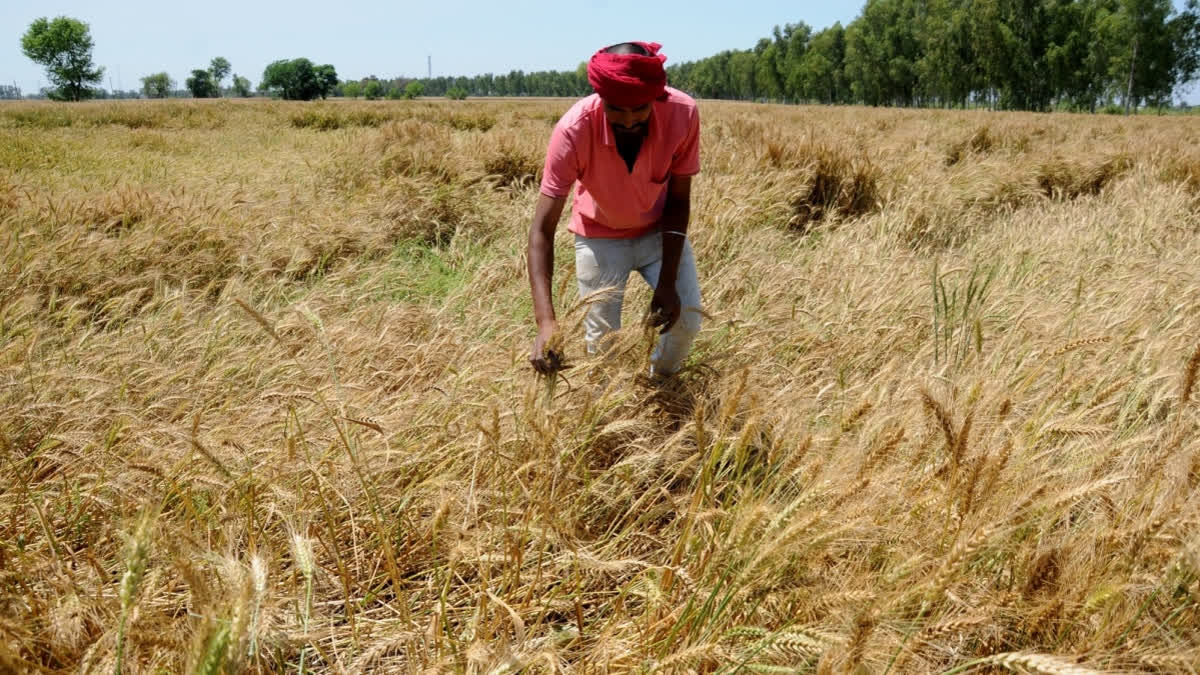
Walk into any village in India today and listen carefully. The bank branch is quiet. The moneylender's house is busy. Farmers are borrowing from neighbours. Families are cutting back on food. Savings have all but disappeared. This is not one village's story. This is the story of rural India in the summer of 2026 — told not by politicians or activists, but by a large, careful survey conducted by NABARD, the government's own apex development bank for agriculture and rural India.
The findings of this survey — covering 20,000 households across 29 states and Union Territories — are a wake-up call for every citizen, every policymaker, and every banker in this country.
What the Survey Found: Three Out of Four Rural Families Are Getting Nowhere
NABARD's Rural Economic Conditions and Sentiments Survey, whose twelfth round was conducted in July 2026, asked a very simple question: is your income higher today than it was a year ago? The answer from rural India was devastating. Only 27 out of every 100 households said yes, their income had gone up. This is the lowest number recorded since NABARD started this survey in September 2024. More than half of all rural households — 52 out of 100 — said their income had not changed at all. Another 20 out of 100 said their income had actually fallen.
Put it simply: three out of every four rural families are either standing still or going backward. In a country that has been celebrating economic growth for years, this is a deeply uncomfortable truth.
The situation has been getting steadily worse. Back in November 2025, 42 out of every 100 rural households reported higher incomes. By July 2026, that number had dropped to just 27. The direction of travel is unmistakable — and it is going in the wrong direction.
Why Are Incomes Shrinking? The Rain and the Rising Prices
The reasons are not hard to find. The monsoon this year has been deeply uneven. In June 2026, rainfall across India was 33% below normal. By early July, it had improved somewhat, but the East and North-East regions were still receiving 37% less rain than usual. Water reservoirs across South India stood at levels 36% lower than they were at this time last year. The area under kharif — the main summer crop — was 21% lower than a year ago. When the rains fail, farmers earn less. When they earn less, everyone in the village earns less — the shopkeeper, the labourer, the small trader, the transport worker.
At the same time, prices have been rising. Fuel costs have gone up. Fertiliser costs have gone up. The world is going through a period of tension and turbulence — wars in faraway places are making commodities more expensive everywhere, and Indian villages are not shielded from these forces. More money going out for daily expenses, less money coming in from crops: this is the rural family's reality in 2026.
How Families Are Coping: Spending More, Saving Less, Borrowing Differently
When income does not grow, families try to manage by cutting back on spending. But there is a limit to how much you can cut when food already takes up more than half of every rupee spent. The survey found that around two-thirds of a rural family's monthly income goes straight to consumption — food, fuel, clothing, daily needs. There is almost nothing left over.
The result is that savings have collapsed. Only 18 out of every 100 rural households reported saving more money this year — the lowest number ever recorded in this survey. People are not saving because they simply cannot. They are spending everything they earn just to keep their families fed and functioning.
The Moneylender's Comeback: A Red Alert for the Banking System
Here is where the story becomes truly alarming — not just for rural families, but for the banking system that is supposed to serve them.
When times get hard and families need to borrow money, where do they go? Ideally, they should go to a bank — where interest rates are regulated, terms are fair, and borrowers have legal protections. But that is not what is happening. According to the NABARD survey, the share of rural households borrowing exclusively from banks and other regulated institutions has fallen from 58% in November 2025 to just 51% in July 2026 — a drop of seven percentage points in just eight months.
Where are the remaining borrowers going? They are going to moneylenders, friends, and relatives — outside the protection of any bank or regulator. Nearly 24 out of every 100 rural borrowers are now relying entirely on informal sources. Among these, most are borrowing from friends and relatives, but 6 out of 100 are going straight to moneylenders. Another 25 out of 100 are borrowing from both banks and moneylenders simultaneously — a dangerous combination.
Why does this matter so much? Because of the price of that money. The average interest rate on informal loans in rural India is 17.77% per year. Compare that with the interest rate on a bank agricultural loan — roughly 7–9% per year for most farmers. When a family borrows at 17.77% to pay for a medical emergency or a daughter's wedding, that debt can spiral out of control very quickly. One bad harvest later, that family may never fully recover.
This is not just a problem for that family. It is a problem for the banks too. When more and more rural borrowers abandon formal credit and drown in high-cost informal debt, they eventually become unable to repay their existing bank loans either. Today's desperate borrower at the moneylender's door is tomorrow's bad loan on a bank's books.
What About Our Banks? Are They Ready for What Is Coming?
India's banks are currently looking reasonably healthy on paper — bad loan ratios are at their lowest levels in over a decade. But that comfort may be misleading. There is always a time gap between when a farmer's income collapses and when a bank's loan goes bad. That time gap — typically one to two years — means the real stress may not show up in bank balance sheets until 2027.
The cooperative banks, which serve the deepest and most remote parts of rural India, are already in serious trouble. Parliamentary data tabled last year showed that more than 400 cooperative banks across the country lost over ₹7,326 crore in just three years. These are the banks that a poor farmer in a small village depends on for his crop loan. If these banks are weakened — or collapse — there is simply no one left to lend to the most vulnerable rural borrowers. The moneylender then becomes not the last resort but the only resort.
What Needs to Change — In Plain Language
First, banks — especially cooperative banks — must be made financially strong and honestly managed. Governance reforms cannot wait. A cooperative bank run by political patronage rather than sound banking principles is a disaster waiting to happen.
Second, reaching farmers with cheap, easy, and quick credit must become a national emergency priority. The government's credit targets are impressive on paper, but paper targets mean nothing if a farmer in a remote village still cannot get a Kisan Credit Card without a mountain of paperwork and a dozen visits to a branch.
Third, the government must take the monsoon shortfall seriously as an economic emergency — not just an agricultural one. Crop insurance must be settled faster. Input subsidies must reach farmers quicker. Rural employment schemes must be activated immediately in drought-affected districts.
The Village Is Telling Us Something. Are We Listening?
India likes to tell a story of shining growth, rising GDP, and a booming economy. That story is true — but it is not the whole story. NABARD's survey tells the other story: of a rural India where three out of four families are stuck, where the moneylender is back with a vengeance, where banks are being quietly abandoned, and where the next wave of bad loans may already be forming in fields and villages far from the trading floors of Mumbai.
The village is not asking for charity. It is asking for fair credit, honest governance, timely relief, and the basic dignity of a banking system that actually reaches it. If we ignore these signals today, we will pay a far heavier price — in human suffering and in broken balance sheets — tomorrow.
(Disclaimer: The opinions expressed in this article are those of the writer. The facts and opinions expressed here do not reflect the views of ETV Bharat)
(The author is a former Senior Editor, The Economic Times, and is currently practicing as an advocate at the Telangana High Court.)
Read More